Canada Pension Plan (CPP) 2026: Understanding Your Retirement Benefits and How to Optimize Your Payout by 1.5%
Advertisements
What if a single, minor adjustment to your financial strategy could permanently boost your pension? With the latest updates rolling out for CPP 2026, unlocking an extra 1.5% on your retirement payout is closer than you think.
National adjustments and fresh insights from industry insiders are fundamentally reshaping how Canadians map out their post-work years. Navigating these subtle shifts isn’t just about understanding federal benefits, it’s about knowing exactly which levers to pull.
As you edge closer to your golden years, leaving money on the table is simply not an option. Here is a straightforward breakdown of what has changed, why it matters, and how to optimize your future government checks.
Understanding the Canada Pension Plan (CPP) in 2026
The Canada Pension Plan remains a cornerstone of retirement income for most Canadians. It provides a foundational level of financial security during old age, disability, or in the event of death.
For 2026, several adjustments are anticipated to ensure the plan’s long-term sustainability and adequacy. These changes are part of ongoing enhancements to the CPP, designed to respond to evolving demographic and economic landscapes.
It is crucial for current and future retirees to grasp these modifications to effectively plan their retirement finances. Staying informed allows for strategic decisions that can significantly impact future payouts.
Key Changes and Enhancements for CPP in 2026
The CPP is undergoing progressive enhancements, with 2026 marking another step in its evolution. These changes aim to increase the maximum CPP retirement benefit, providing greater financial stability for recipients.
The primary enhancement involves a gradual increase in both contributions and benefits. This ensures that future retirees receive a higher percentage of their earnings in retirement, reflecting a more robust pension system.
These enhancements are designed to address concerns about retirement readiness and poverty among seniors. The goal is to provide a more substantial safety net, moving beyond the base CPP to offer greater income replacement.
Increased Contribution Rates and Earnings Ceilings
Starting in 2024, the CPP introduced a second earnings ceiling, known as the Year’s Additional Maximum Pensionable Earnings (YAMPE). This means that contributors will pay CPP contributions on a higher portion of their earnings.
For 2026, these ceilings are expected to continue their upward trajectory, impacting both employers and employees. While this means higher current contributions, it directly translates to higher potential future benefits.
- Higher earnings thresholds for contributions.
- Increased contributions from both employees and employers.
- Direct correlation between higher contributions and future benefit amounts.
Impact on Retirement Benefit Calculations
The enhanced CPP will result in higher retirement benefits for those who contribute more under the new rules. The additional contributions fund a new component of the CPP, leading to increased payouts.
Individuals who contribute for a significant number of years under the enhanced CPP will see a noticeable difference in their monthly retirement cheques. This is a direct return on their increased contributions.
The calculation methodology will factor in these additional contributions, ensuring a fairer and more substantial benefit for those who have paid into the enhanced system over their working lives.
Eligibility Requirements for CPP Benefits in 2026
To qualify for CPP retirement benefits, individuals must have made at least one valid contribution to the plan. The standard age to begin receiving benefits is 65, but options exist for earlier or later commencement.
The amount of benefit received is directly tied to an individual’s average earnings throughout their contributing years. The more one contributes, up to the annual maximum, the higher their potential benefit.
Understanding these fundamental eligibility criteria is the first step in planning for your CPP. It helps to set realistic expectations for your retirement income and allows for informed decisions regarding when to start receiving benefits.
Strategies to Optimize Your CPP Payout by 1.5%
Optimizing your CPP payout, particularly aiming for an increase of 1.5%, involves strategic decisions regarding when to start receiving your benefits. This percentage increase is a significant boost to your long-term retirement income.
The key to achieving this optimization often lies in understanding the deferral options available. Delaying the start of your CPP benefits beyond age 65 can lead to a substantial increase in your monthly payments.
Financial advisors frequently highlight deferral as one of the most effective ways to enhance CPP benefits. This strategy, when suitable for your financial situation, can provide a lasting advantage throughout retirement.
The Power of Deferral: Starting Benefits Later
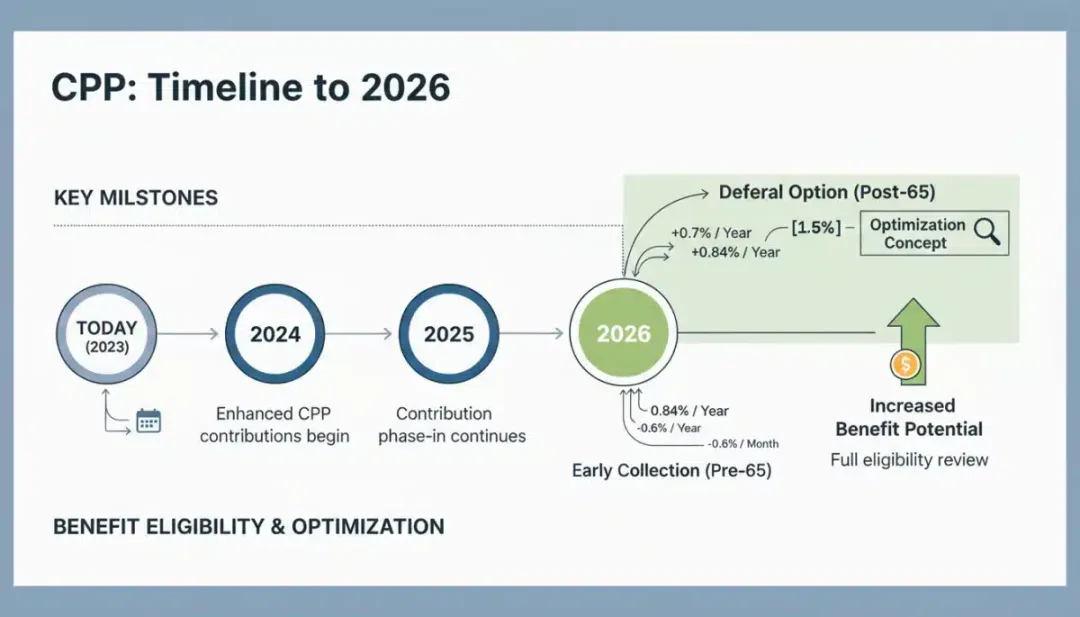
For each month you defer receiving your CPP retirement pension after age 65, up to age 70, your monthly payment increases by 0.7%. This translates to an 8.4% increase per year of deferral.
By carefully calculating the optimal deferral period, individuals can significantly boost their overall lifetime benefits. For instance, deferring for just a few months can easily achieve a 1.5% increase or more.
This strategy is particularly beneficial for those who are still working past 65 or have other sources of income to cover their living expenses. It allows their CPP to grow, providing a larger, inflation-protected income stream later.
- Deferring benefits past age 65 increases monthly payments.
- A 0.7% increase per month of deferral, up to age 70.
- Strategic deferral can lead to a significant lifetime benefit increase.
Considering Early Commencement: Potential Trade-offs
While deferral offers higher payouts, some individuals may choose to start their CPP benefits as early as age 60. However, this comes with a reduction in monthly payments.
Starting at age 60 results in a reduction of 0.6% for each month before age 65, totaling a 36% reduction if started at the earliest possible age. This decision should align with one’s immediate financial needs and health considerations.
It is essential to weigh the immediate need for income against the long-term impact of reduced payments. For some, early commencement is a necessity, while for others, it’s a trade-off that needs careful consideration.
Maximizing Your CPP with Additional Contributions
Beyond deferral, contributing more to the CPP during your working years can also lead to higher benefits. The enhanced CPP design rewards those who contribute on higher earnings.
If you have periods of lower earnings or non-contributory years, there are provisions like the general drop-out provision that can help. This provision automatically drops a certain number of your lowest-earning years from the benefit calculation.
Understanding how these provisions work and how they interact with your contribution history is vital for maximizing your eventual payout. It ensures that your benefit calculation accurately reflects your peak earning potential.
Understanding the Impact of Inflation and Cost of Living Adjustments
The Canada Pension Plan benefits are indexed to the Consumer Price Index (CPI), ensuring that your purchasing power is maintained over time. This is a crucial feature that protects retirees from inflation.
Each January, CPP benefits are adjusted to reflect changes in the cost of living. This automatic adjustment means that the real value of your pension remains stable, providing consistent financial security.
This indexing is a significant advantage of the CPP, distinguishing it from many other retirement income sources that may not offer such inflation protection. It provides peace of mind that your benefits will keep pace with rising expenses.
Expert Insights and Financial Planning for CPP 2026
Financial advisors consistently stress the importance of proactive planning when it comes to CPP benefits. Understanding the nuances of the plan, especially with the 2026 enhancements, is key to an optimized retirement.
Consulting with a financial expert can provide personalized guidance tailored to your specific situation. They can help analyze your contribution history, estimate future benefits, and strategize the optimal timing for commencement.
Moreover, integrating your CPP strategy with other retirement savings and investments is crucial for a holistic financial plan. The CPP is a foundational piece, but it should complement other income streams for comprehensive retirement security.
Resources and Where to Find More Information
Service Canada is the primary source for official information regarding the Canada Pension Plan. Their website offers detailed guides, calculators, and application forms for all CPP-related matters.
Additionally, various financial institutions and reputable financial planning websites provide valuable insights and tools to help you understand and plan for your CPP benefits. Always cross-reference information with official government sources.
Staying informed through these channels ensures you have access to the most accurate and up-to-date information. This proactive approach is essential for making well-informed decisions about your retirement finances.
| Key Point | Brief Description |
|---|---|
| CPP 2026 Enhancements | Gradual increase in contributions and benefits for higher retirement income. |
| Optimize by Deferral | Delaying CPP past 65 increases monthly payments by 0.7% per month. |
| Additional Contributions | Higher contributions on earnings up to YAMPE lead to greater benefits. |
| Inflation Protection | CPP benefits are indexed to CPI, protecting purchasing power in retirement. |
Frequently Asked Questions About CPP 2026 Optimization
What are the main changes to Canada Pension Plan (CPP) for 2026?▼The main changes for 2026 are part of the ongoing CPP enhancement, involving higher contribution rates and the introduction of the Year’s Additional Maximum Pensionable Earnings (YAMPE). These adjustments aim to gradually increase the maximum CPP retirement benefit for future retirees who contribute more under the enhanced plan.
How can I optimize my CPP payout by 1.5%?▼Optimizing your CPP payout by 1.5% can often be achieved by strategically deferring the start of your benefits. For every month you delay past age 65, up to age 70, your monthly payment increases by 0.7%. A few months of deferral can easily reach or exceed a 1.5% increase.
What is the Year’s Additional Maximum Pensionable Earnings (YAMPE)?▼YAMPE is a second earnings ceiling introduced in 2024 as part of the enhanced CPP. It means that individuals will contribute on a higher portion of their earnings above the first earnings ceiling. These additional contributions directly fund the enhanced portion of their future CPP benefits.
Is starting CPP early (before age 65) a good strategy?▼Starting CPP benefits before age 65 (as early as age 60) results in a permanent reduction of your monthly payments. While it provides earlier income, it’s generally not ideal for maximizing lifetime benefits. This strategy should only be considered if immediate financial need outweighs the long-term benefit reduction.
How do inflation and cost of living adjustments affect my CPP?▼CPP benefits are indexed to the Consumer Price Index (CPI) and adjusted annually in January. This means your payments increase with the cost of living, protecting your purchasing power from inflation throughout your retirement. This feature ensures the real value of your pension remains stable over time.
What This Means for Your Retirement Planning
The updates for the Canada Pension Plan (CPP) 2026 highlight the ongoing evolution of Canada’s retirement system.
It underscores the importance of informed decision-making to secure your financial future. As the CPP continues to adapt, proactively engaging with these changes will be key.
Canadians should closely monitor official announcements from Service Canada and consult financial professionals.
This ensures that their retirement planning aligns with the latest regulations and opportunities for benefit maximization. Understanding the deferral benefits and enhanced contribution impacts is crucial.
Ultimately, the goal is to optimize your CPP 2026 to provide a robust and sustainable income stream throughout your retirement years. Strategic planning now will yield significant dividends later, ensuring greater peace of mind and financial stability.