Navigating the Disability Tax Credit (DTC) in 2026: A Practical Guide to Claiming Up to $8,870
Advertisements
Navigating tax season can be overwhelming, but securing the Disability Tax Credit is a vital step toward easing your household budget. If you or a loved one live with a prolonged impairment, this critical government provision is designed to significantly lower your tax burden.
The Canada Revenue Agency continuously updates its thresholds, making it essential to understand the latest qualification criteria. Maximizing this specialized tax reduction ensures you do not leave thousands of dollars of rightful medical expense relief on the table.
This guide breaks down exactly how to secure up to $8,870 in cumulative benefits for the 2026 tax year. Let’s walk through the application process together so you can claim the financial support your family deserves.
Understanding the Disability Tax Credit (DTC) in 2026
The Disability Tax Credit (DTC) is a federal non-refundable tax credit that helps people with disabilities or their supporting family members reduce the amount of income tax they have to pay.
It aims to recognize the additional costs associated with living with a severe and prolonged impairment.
For 2026, the core principles of the DTC are expected to remain consistent, though annual adjustments to credit amounts and potential minor procedural updates are always a possibility. Staying abreast of these changes is crucial for successful applications and maximizing eligible benefits.
This credit is not a direct payment but rather a reduction in taxable income, which can translate into significant savings. It also serves as a gateway to other federal programs and benefits, making its qualification particularly impactful for many Canadians.
What is the Disability Tax Credit?
The Disability Tax Credit is a federal tax measure designed to provide financial relief to individuals who experience significant challenges due to a severe and prolonged mental or physical impairment.
It acknowledges the extra expenses often incurred by those living with disabilities or their caregivers.
Qualifying for the DTC can unlock access to several other benefits, such as the Registered Disability Savings Plan (RDSP) and the Canada Caregiver Credit, amplifying its financial impact.
This makes the initial application for the Disability Tax Credit a foundational step for comprehensive disability support in Canada.
The credit amount is determined by a base amount and, for those under 18, a supplement for children with disabilities, both indexed to inflation annually. Understanding these components is key to grasping the full potential of the Disability Tax Credit.
Changes and Expectations for 2026
While major structural overhauls to the Disability Tax Credit are infrequent, the Canada Revenue Agency (CRA) routinely updates specific figures and may refine application guidelines.
For 2026, Canadians should anticipate inflationary adjustments to the base amount and the supplement for children.
Monitoring official CRA announcements as the 2026 tax year approaches will be essential to catch any procedural modifications or new interpretive policies. These updates, though often subtle, can influence how medical practitioners complete forms and how applications are assessed.
It is also prudent to be aware of any legislative discussions that could impact disability benefits, as these sometimes lead to future adjustments in programs like the Disability Tax Credit.
Proactive information gathering ensures applicants are always working with the most current requirements.
Eligibility Criteria for the Disability Tax Credit
To qualify for the Disability Tax Credit, an individual must have a severe and prolonged mental or physical impairment, as certified by a medical practitioner. The impairment must be present for a continuous period of at least 12 months.
The CRA defines “severe and prolonged” based on specific criteria that relate to the individual’s ability to perform basic activities of daily living. These criteria are rigorously applied to ensure the credit is directed to those who genuinely meet the requirements.
Understanding these precise eligibility conditions is the most critical first step in successfully applying for the Disability Tax Credit. Misinterpretations can lead to application delays or rejections, making accurate self-assessment paramount.
Defining “Severe and Prolonged Impairment”
A severe impairment means that the individual is either blind, or is markedly restricted in at least one of the basic activities of daily living, or requires life-sustaining therapy.
Markedly restricted implies that, even with appropriate therapy, medication, or assistive devices, the individual is unable or takes an inordinate amount of time to perform a basic activity of daily living.
A prolonged impairment must have lasted, or be expected to last, for a continuous period of at least 12 months. This continuity is a key factor, distinguishing temporary conditions from those that meet the DTC’s criteria for ongoing support.
The CRA assesses these restrictions based on their cumulative effect, meaning that while one condition might not be severe enough on its own, the combined effect of multiple impairments could lead to eligibility for the Disability Tax Credit.
Basic Activities of Daily Living
- Walking: Limited ability to walk even with aids.
- Feeding: Significant difficulty preparing or consuming food.
- Dressing: Inability to dress or undress independently.
- Mental Functions: Marked restriction in adaptive functioning, memory, or problem-solving.
- Speaking: Impairment in communicating verbally.
- Hearing: Significant difficulty perceiving sounds.
- Eliminating: Requiring significant time or assistance with bowel or bladder functions.
The assessment often considers the time it takes to perform these activities, the effort required, and the safety risks involved. It is not merely about having a diagnosis, but about how the impairment functionally limits daily life, impacting the individual’s ability to live independently.
The cumulative effect of multiple restrictions is an important consideration. Sometimes, no single activity is markedly restricted, but the combined effect of several mild restrictions can result in eligibility for the Disability Tax Credit.
The Application Process for the DTC in 2026
Applying for the Disability Tax Credit involves a multi-step process, primarily centered around completing Form T2201, Disability Tax Credit Certificate. This form requires detailed input from both the applicant and a qualified medical practitioner.
Accurate and thorough completion of this form is paramount, as it serves as the primary evidence for the CRA’s assessment of eligibility. Any omissions or unclear descriptions can lead to delays or requests for further information, prolonging the application timeline.
Understanding each stage of this process, from gathering medical evidence to submitting the final form, will streamline your application for the Disability Tax Credit and increase your chances of approval.
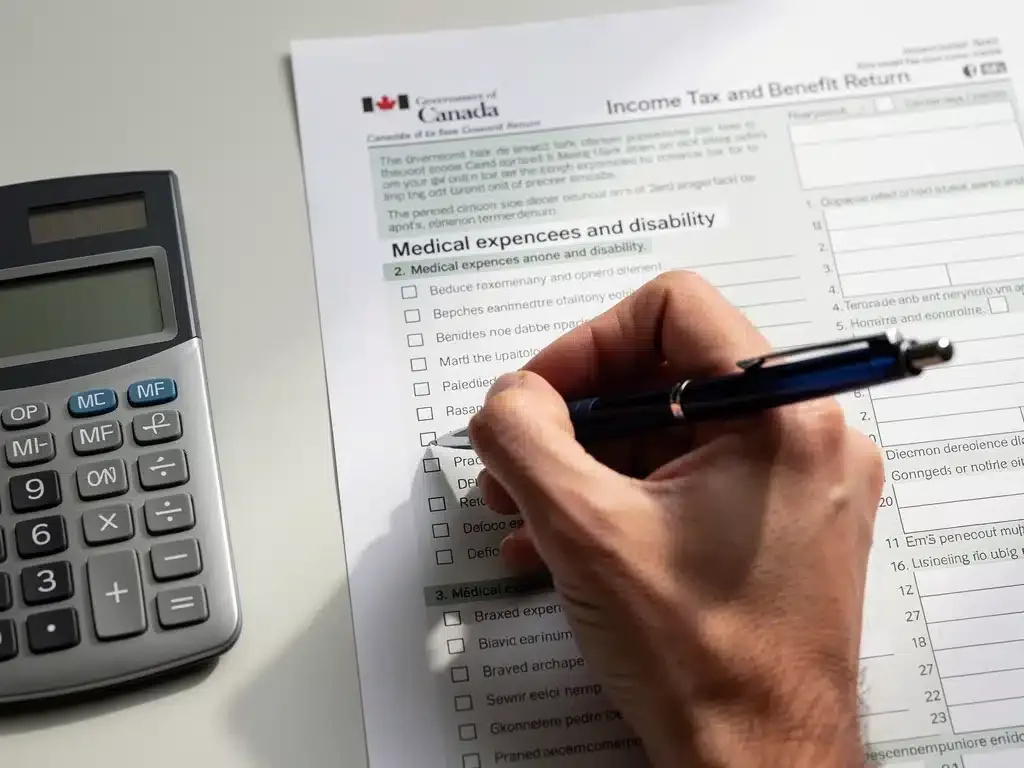
Completing Form T2201, Disability Tax Credit Certificate
The Form T2201 is divided into two main parts: Part A, which is completed by the applicant or their representative, and Part B, which must be completed and certified by a qualified medical practitioner.
Part A includes basic personal information and details about the representative, if applicable.
Part B requires the medical practitioner to describe the nature of the impairment, its duration, and how it affects the individual’s ability to perform basic activities of daily living.
This section is critical, as it provides the medical evidence the CRA uses to determine eligibility for the Disability Tax Credit.
It is advisable to provide your medical practitioner with any relevant medical reports or assessments that can help them accurately complete Part B. Clear and comprehensive documentation strengthens your application for the Disability Tax Credit.
Role of Medical Practitioners
A qualified medical practitioner must certify the nature and extent of the impairment on Form T2201.
The type of practitioner required depends on the nature of the disability; for example, a medical doctor, optometrist, audiologist, occupational therapist, physiotherapist, psychologist, or speech-language pathologist may be eligible.
Their role is to provide an objective assessment of how the impairment affects the individual’s daily life, not just to confirm a diagnosis.
They must clearly articulate how the condition causes a marked restriction or requires life-sustaining therapy, aligning with CRA’s definitions for the Disability Tax Credit.
Communication with your medical professional is key. Ensure they understand the specific criteria for the Disability Tax Credit and how their medical assessment contributes to the application’s success. This collaboration significantly improves the clarity and strength of your submission.
Maximizing Your Disability Tax Credit Claim
Beyond simply qualifying, understanding how to maximize the value of your Disability Tax Credit is crucial. This involves knowing how the credit is calculated, how it interacts with other benefits, and how to claim it effectively on your tax return.
The DTC can be transferred to a supporting family member, which is a significant advantage for those who may not have enough taxable income to fully utilize the credit themselves. This transferability broadens the financial relief available to households.
Strategic tax planning around the Disability Tax Credit can lead to substantial annual savings, making it more than just a reduction in taxes, but a cornerstone of financial stability for many Canadians with disabilities.
Calculating the DTC Amount
The Disability Tax Credit consists of a base amount and, for those under 18, a supplement for children with disabilities. Both amounts are indexed annually to inflation, meaning they increase slightly each year to account for the rising cost of living.
For the 2026 tax year, while exact figures will be released closer to the date, these amounts will be multiplied by the lowest federal income tax rate (currently 15%). This calculation determines the actual tax reduction you will receive from the Disability Tax Credit.
The federal amount can be combined with provincial and territorial disability tax credits, further increasing the overall financial benefit. Understanding these combined effects allows for a more accurate estimation of your potential savings from the Disability Tax Credit.
Transferring the Credit to a Supporting Person
If the person with the disability does not need the full amount of the Disability Tax Credit to reduce their own tax payable to zero, the unused portion can be transferred to a supporting family member. This is a common and highly beneficial aspect of the DTC.
Eligible supporting individuals include a spouse, common-law partner, or another family member who consistently supports the person with the disability. This support typically involves providing food, shelter, or clothing, and being able to claim certain caregiving amounts.
The transferability feature ensures that the financial benefit of the Disability Tax Credit is utilized to its fullest extent within the family unit, providing broader relief for the costs associated with supporting a person with a disability.
Common Pitfalls and How to Avoid Them
Despite its significant benefits, applying for the Disability Tax Credit can be complex, and several common mistakes can lead to delays or denials. Being aware of these pitfalls can help applicants navigate the process more smoothly and successfully.
One frequent issue is incomplete or insufficient medical documentation, which fails to clearly demonstrate how the impairment meets the CRA’s strict criteria. Another is a misunderstanding of the definition of “markedly restricted” or “life-sustaining therapy.”
Proactive preparation and careful attention to detail are your best defenses against these common problems, ensuring your application for the Disability Tax Credit is as robust as possible.
Incomplete or Incorrect Information
A primary reason for delays or rejections in Disability Tax Credit applications is incomplete or incorrect information on Form T2201. This can range from minor omissions in personal details to significant gaps in the medical practitioner’s description of the impairment.
Ensure all sections of both Part A and Part B are thoroughly completed, and that the medical information precisely addresses how the impairment affects the basic activities of daily living according to CRA guidelines. Double-checking every entry can save considerable time and frustration.
If you are unsure about any section, it is always better to seek clarification from the CRA or a tax professional rather than submitting potentially erroneous information. Accuracy is key to a smooth Disability Tax Credit application.
Appealing a Denied DTC Application
If your Disability Tax Credit application is denied, it does not mean the process is over. You have the right to appeal the decision, and many successful claims are approved after an initial denial through the appeal process.
The first step is to carefully review the CRA’s explanation for the denial to understand the specific reasons. Often, it relates to insufficient medical information or a misinterpretation of how the impairment restricts daily activities, which can be clarified with additional documentation.
Gathering more medical evidence, seeking a second opinion from another qualified practitioner, or requesting a reassessment by the CRA are viable options. Professional assistance from a tax lawyer or a specialized DTC service can be invaluable during an appeal for the Disability Tax Credit.
Impact of the Disability Tax Credit on Other Benefits
The Disability Tax Credit is not just a standalone tax reduction; it acts as a gateway to several other important federal and provincial programs. Qualifying for the DTC can unlock access to significant additional financial support and tax benefits.
Understanding these interconnected benefits is crucial for holistic financial planning for individuals with disabilities and their families. The DTC’s ripple effect can amplify overall support, making its acquisition a foundational step.
From long-term savings plans to direct financial assistance, the Disability Tax Credit plays a pivotal role in Canada’s disability support framework, providing access to resources that might otherwise be unavailable.
Registered Disability Savings Plan (RDSP)
One of the most significant benefits linked to the Disability Tax Credit is eligibility for the Registered Disability Savings Plan (RDSP). The RDSP is a long-term savings plan designed to help people with disabilities save for their future.
The federal government provides generous grants and bonds to eligible RDSPs, significantly boosting the savings of individuals with disabilities. Without being approved for the Disability Tax Credit, an individual cannot open an RDSP or receive these government contributions.
The grants and bonds can amount to tens of thousands of dollars over the lifetime of the plan, making the RDSP an incredibly powerful tool for financial security. This direct link highlights why qualifying for the Disability Tax Credit is so vital.
Canada Caregiver Credit and Other Programs
Beyond the RDSP, the Disability Tax Credit can also enable a supporting individual to claim the Canada Caregiver Credit, which provides further tax relief for those caring for a dependent with a disability. This credit helps offset the financial burden of caregiving.
Additionally, some provincial and territorial programs may use DTC eligibility as a criterion for accessing local disability benefits or services. This means the federal credit can open doors to a broader network of support at various government levels.
It is important for individuals and families to research all potential benefits that become accessible once the Disability Tax Credit is approved. Maximizing all available support requires a comprehensive understanding of these interconnected programs.
Preparing for Your 2026 DTC Application
Proactive preparation is key to a smooth and successful Disability Tax Credit application for the 2026 tax year. Gathering all necessary documentation and understanding the requirements well in advance can significantly reduce stress and potential delays.
This preparation involves not only medical records but also understanding how to communicate effectively with your medical practitioner about the specific needs of the Form T2201. Being organized ensures a comprehensive submission.
Starting early allows ample time to address any potential issues, seek professional advice if needed, and ensure all criteria for the Disability Tax Credit are met before the tax season rush.
Gathering Medical Documentation
Before approaching your medical practitioner to complete Form T2201, collect all relevant medical reports, assessments, and diagnostic information pertaining to the impairment. This includes reports from specialists, therapists, and any other healthcare providers.
These documents provide your medical practitioner with a comprehensive overview of your condition and its impact, enabling them to accurately and thoroughly complete Part B of the form. The more detailed the evidence, the stronger your Disability Tax Credit application will be.
Keep organized copies of all medical records, as they may be required if the CRA requests further information or if an appeal becomes necessary. Strong documentation is the backbone of a successful Disability Tax Credit claim.
Seeking Professional Assistance
While it is possible to apply for the Disability Tax Credit independently, many individuals find it beneficial to seek professional assistance. Tax professionals, disability advocates, or specialized DTC service providers can offer invaluable guidance.
These experts are familiar with the intricacies of CRA’s requirements and can help ensure Form T2201 is completed accurately and persuasively. They can also assist with appeals if an application is initially denied, leveraging their experience to present a stronger case.
Considering the significant financial benefits of the Disability Tax Credit, investing in professional help can often pay for itself through a higher likelihood of approval and maximized claims. This support can alleviate much of the administrative burden.
The Long-Term Financial Impact of the DTC
Securing the Disability Tax Credit extends beyond immediate tax savings; it forms a cornerstone of long-term financial stability and planning for individuals with disabilities and their families. Its impact can be felt for years, not just in the tax year of application.
The cumulative effect of annual tax reductions, combined with access to programs like the RDSP, creates a robust financial safety net. This allows for better planning for future needs, whether it’s for education, housing, or ongoing care.
Understanding this enduring value underscores the importance of proactively pursuing and maintaining eligibility for the Disability Tax Credit throughout the years.
Planning for the Future with the DTC
With the Disability Tax Credit in place, families can engage in more effective long-term financial planning. The predictable annual tax relief helps budget for disability-related expenses, easing financial strain.
Moreover, the ability to contribute to an RDSP with government matching grants and bonds provides a powerful vehicle for building significant savings. This ensures a more financially secure future for the individual with the disability, fostering greater independence.
Utilizing the Disability Tax Credit as a strategic financial tool allows for better preparation for life’s milestones and unexpected challenges, providing peace of mind and enhanced quality of life.
Advocacy and Awareness
The importance of the Disability Tax Credit also extends to broader advocacy and awareness efforts. By understanding and utilizing this credit, individuals and families contribute to the overall recognition of the financial needs of people with disabilities.
Increased awareness can lead to further improvements in government support programs and a more inclusive approach to tax policy. Sharing experiences and knowledge about the Disability Tax Credit empowers others to claim their rightful benefits.
This collective engagement helps ensure that the Disability Tax Credit continues to evolve as an effective and accessible support mechanism for Canadians with disabilities, reinforcing its critical role in the national social safety net.
| Key Aspect | Description |
|---|---|
| Eligibility | Severe and prolonged impairment, certified by a medical professional. |
| Application | Complete Form T2201; Part B requires medical practitioner’s certification. |
| Maximize Claim | Understand calculation, transferability, and linked benefits like RDSP. |
| Appeal Process | Review denial reasons, gather more evidence, or seek professional help. |
Frequently Asked Questions About the Disability Tax Credit
What is the maximum amount I can claim with the Disability Tax Credit in 2026?▼While the exact indexed amounts for 2026 will be confirmed by the CRA, the federal portion of the Disability Tax Credit can translate to approximately $8,870 or more in tax savings for eligible individuals, including the supplement for children with disabilities, if applicable.
Who is considered a “qualified medical practitioner” for the DTC application?▼A qualified medical practitioner can be a medical doctor, optometrist, audiologist, occupational therapist, physiotherapist, psychologist, or speech-language pathologist, depending on the nature of the impairment. The CRA specifies which professional can certify each type of impairment on Form T2201.
Can I apply for the Disability Tax Credit for previous tax years?▼Yes, if you were eligible for the Disability Tax Credit in previous years but did not claim it, you can request an adjustment to your tax returns for up to 10 previous calendar years. This can result in significant retroactive tax refunds.
What happens if my Disability Tax Credit application is denied?▼If your application is denied, you have the right to appeal the decision. Start by reviewing the CRA’s reasons for denial. You can then provide additional medical information, seek another medical opinion, or consider requesting a formal review of your file.
How does the Disability Tax Credit affect other government benefits?▼Qualifying for the Disability Tax Credit is a prerequisite for accessing other significant benefits, such as the Registered Disability Savings Plan (RDSP) and the Canada Caregiver Credit. It can also open doors to various provincial and territorial disability support programs, amplifying overall financial assistance.
Looking Ahead
The landscape of the Disability Tax Credit (DTC) for 2026 continues to evolve, with its fundamental role in Canadian financial support remaining steadfast.
Future developments will likely focus on inflationary adjustments to benefit amounts and potential refinements to application processes to enhance accessibility.
It is important for individuals and families to stay informed through official CRA channels and medical professionals.
Proactive engagement with the application process for the Disability Tax Credit ensures that eligible Canadians can effectively claim the support they are entitled to, fostering greater financial stability and inclusion.